

- 2GIT retirement signals a decade-long GSA consolidation cycle
- Obligations data leads GSA retirement announcements by months
- Four of five agencies share PSC DA01 as top IT code
- NAICS 541512 tops IT obligations across all five major agencies
- Evaluate successor vehicles by agency buying patterns, not marketing
GSA didn’t issue a press release when it quietly stopped taking new task order competitions on 2GIT. The notice landed the way most vehicle news does now: a short item in a federal-IT roundup like Dispatch, easy to skim past unless you hold a position on that BPA. By the time capture teams noticed, the real story had run for months in the obligations data — agencies that drove 2GIT’s volume had already shifted budget elsewhere.
A retirement notice is a lagging indicator; the obligations trend line is the leading one. Vendors who treat the GSA announcement as the starting gun are already behind.
Why Does GSA Keep Retiring IT Vehicles Like 2GIT?
2GIT’s retirement isn’t an isolated event — it’s the latest turn of a consolidation cycle GSA has run for over a decade. The logic is category management: fewer, larger, tightly governed vehicles are easier to steer compliant spend through, and easier for contracting officers to defend. We covered the compliance angle in an earlier piece on federal guided buying; this one covers the mechanism underneath it.
| What’s Changing | What Stays the Same | What to Watch |
|---|---|---|
| No new task order competitions under 2GIT | Existing task orders and IDV child orders run to completion | Whether obligations on the vehicle are active or tapering |
| GSA stops promoting the vehicle | Current contractor revenue on live orders | Which agencies drove the most volume before the notice |
| Forward pipeline on the vehicle closes | Agency IT demand itself — it doesn’t vanish | Where that demand resurfaces next |
Each round raises the stakes of whatever vehicle survives: fewer options means bigger, fewer awards, the dynamic behind OASIS+’s climb toward $47 billion.
What Happens to Vendors Holding Positions on a Retired Vehicle?
Current revenue is usually safe; the pipeline is what disappears. IDV child orders placed before a BPA stops accepting new competitions typically run their full period of performance. The risk sits a year or two out, in competitions that would have run on 2GIT but now won’t.
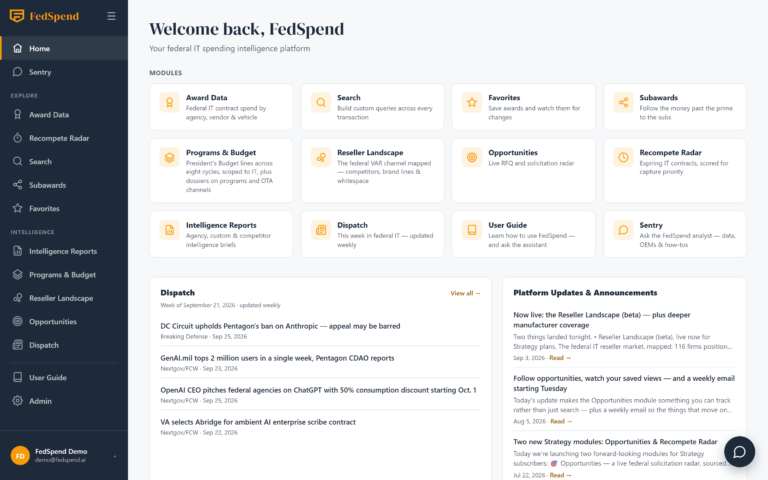
That distinction changes what to monitor. A press release says nothing about whether your task orders still draw obligations; transaction history and IDV child-order rollups do. An order posting obligations monthly is different from one that stopped moving a year ago, and the Award Data platform builds that rollup view so a vendor can tell the two apart.
Smaller shops feel this hardest. A diversified prime absorbs a lost access point; a five-person BD team built around one vehicle does not, the same squeeze we’ve written about for small and mid-size federal IT vendors without a dedicated capture department.
Where Is the IT Spend Actually Landing Next?
The vehicle changes; the category codes barely move. Across the five largest IT spenders in FedSpend’s dataset, one NAICS code — 541512, Computer Systems Design Services — tops obligations no matter which BPA, IDIQ, or GWAC carried the money. That’s more durable to track than any vehicle’s brand name.
Explore federal IT spending patterns free
Start a FedSpend trial to discover growth opportunities in $675B+ of federal IT awards.
DoD’s Big Two: Air Force and Navy
The Air Force obligated $12.0 billion in IT and telecom in fiscal 2025 across 22,512 transactions, averaging near $534,000 each. Roughly 20% of that ($2.39 billion) sat in PSC DA01, business-application and app-dev labor. The Navy obligated $10.1 billion across 44,509 transactions, averaging closer to $226,000 — spread across far more, smaller actions.
Civilian Agencies Lean Even Harder on DA01
The VA obligated $9.4 billion in fiscal 2025, and DA01 alone was roughly 30% of it — the highest share of the five, consistent with VA’s shift toward SaaS. HHS obligated $9.2 billion in fiscal 2024, DA01 at about 25%. The Army is the outlier: its top code in fiscal 2025 was 5810, communications security equipment, just over 10% of its $9.4 billion total — a reminder “IT spend” still means hardware at some departments.
| Agency | Fiscal Year | Total IT Obligations | Top PSC | Top NAICS |
|---|---|---|---|---|
| Air Force | FY2025 | $12.03B | DA01 – App Dev (Labor) | 541512 |
| Navy | FY2025 | $10.07B | DA01 – App Dev (Labor) | 541512 |
| Veterans Affairs | FY2025 | $9.40B | DA01 – App Dev (Labor) | 541512 |
| Army | FY2025 | $9.41B | 5810 – Comm Security Equip. | 541512 |
| Health & Human Services | FY2024 | $9.19B | DA01 – App Dev (Labor) | 541512 |
Four of five agencies share the same top PSC and all five share the same top NAICS. That’s the pattern worth underwriting a capture plan on.
How Do You Evaluate a Successor Vehicle Before You Commit Capture Time?
Check the buyers before you check the vehicle. A marketing deck will call the successor the next big thing; obligations data tells you whether that’s already true.
- Map who drove volume on the retiring vehicle — which bureaus placed dollars, not just who was authorized to use it.
- Confirm those buyers are early adopters of the successor. Heavy marketing with no obligations yet is a bet, not a signal.
- Pull recompete timing on contracts tied to the old vehicle, the same discipline behind how many offers federal IT recompetes typically draw.
- Weight the bet by agency obligation patterns, not announcement language. No movement within a couple quarters of 2GIT’s wind-down is a data point.
GSA’s notice won’t tell you any of this. Recompete Radar scores that timing risk — size, contestability, how soon an IDV shell closes — so a capture team isn’t guessing which re-competitions to chase first.
How Do You Track Consolidation Without Waiting on the Next GSA Notice?
The fix is a standing view of obligations, not a research sprint every time a vehicle sunsets. Federal IT spending data is technically public on USAspending and FPDS; functionally it’s scattered across formats no BD team can reconcile monthly — the gap our deep dive on federal IT spending intelligence laid out.
- Obligations by agency, PSC, and NAICS, refreshed monthly
- DoD broken out by component — Army, Navy, Air Force, DLA, DISA — not lumped as “Defense”
- Contract vehicle tagged on every award, so consolidation shows up as a pattern, not a surprise
- IDV child-order history separating active obligations from dormant paper
Guided buying isn’t a phase GSA will outgrow; it’s the operating model now, and 2GIT is just the latest vehicle folded into it. Treat obligations tracking as infrastructure, not a scramble every time a program office sends a notice.
The Vehicle Was Never the Asset
Vendors losing sleep over a BPA’s name are solving the wrong problem. Air Force, Navy, VA, Army, and HHS didn’t need less application-development or systems design work the week 2GIT stopped taking orders — they started buying it elsewhere. Chase the access point. But underwrite the chase with obligations data, not whatever the next capture deck claims, because the deck was written to win your attention, not your recompete.
